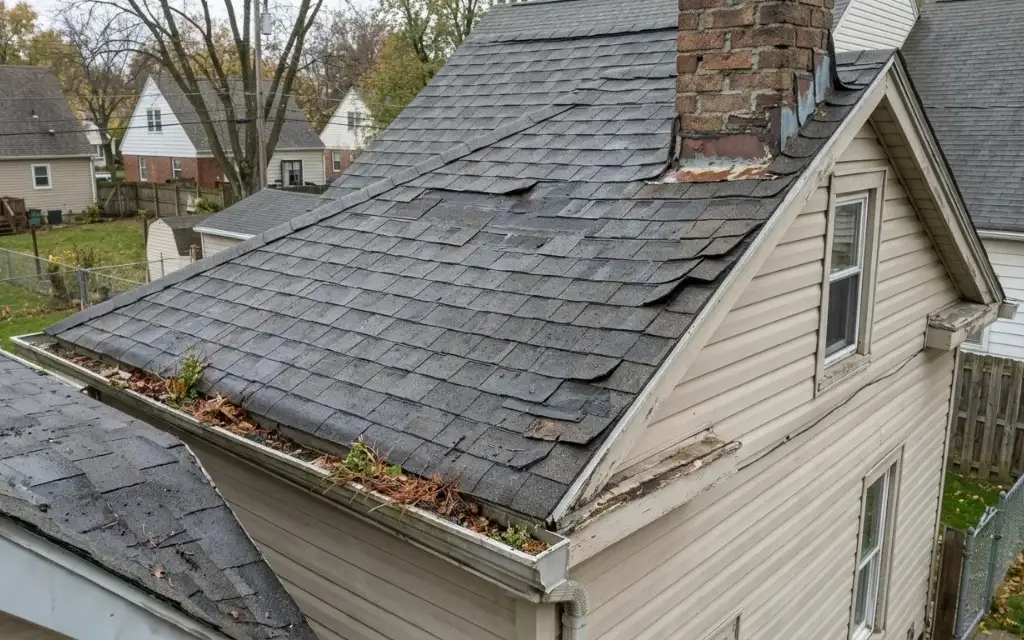
You noticed the stain on the ceiling first. Then they drip into the bucket. Then the quote came back at $14,000 and your stomach dropped a little.
You’re not alone. Most people don’t have a roof’s worth of cash just sitting around. In Toledo, a new asphalt shingle roof usually costs $12,000 to $18,000. Metal runs $25,000 to $35,000. That’s a lot of money to find on short notice. So let’s talk about how people actually pay for it, what each option really costs, and a few local programs most homeowners have never heard of.
How much do you actually need to finance?
Don’t guess. Get a real number first. Roof size, pitch, the material you pick and the shape of the wood underneath all change the price. That wood is the sneaky part. Nobody can see it until the old shingles come off. A free roof inspection with photos tells you what you’re really dealing with, so you don’t borrow too little and come up short halfway through.
And be honest with yourself about waiting. A small leak in fall can turn ugly by January once ice dams show up. Water soaks into the decking. Then it’s in the drywall. Now you need more than a roof replacement. Yes, borrowing costs money. Waiting does too, it just sends the bill later.
Check your insurance before you borrow a dime
If a storm did this, call your insurance first. Wind, hail, a tree limb through the shingles. That kind of damage is often covered. Old age and normal wear isn’t. Get the damage documented before you sign anything. We walk through how we photograph damage and meet your adjuster on our insurance roof claims assistance page, and our storm damage roof repair guide covers the rest.
Now the part that catches people off guard. A lot of Ohio insurers have quietly switched older roofs to actual cash value coverage. That means they take off for depreciation. So if your roof is 17 years old, the check might be way smaller than you expected. Pull out your policy or call your agent today and ask. Is my roof covered at replacement cost or actual cash value? Better to find out now than after a storm.
Local help most Toledo homeowners never hear about
A lot of people pay full price without knowing these exist. Check which one fits where you live and what you earn.
- City of Toledo Rooftops Repair Program. It gave some low and moderate income homeowners grants of $15,000 to $20,000, picked by lottery. It’s closed to new applicants right now, so keep an eye on the city’s housing page in case it opens again.
- Maumee Valley Habitat for Humanity. Helps Lucas County homeowners earning under 60% of the area median income with health and safety repairs. You put in some volunteer hours, and they offer 0% interest payment plans.
- Lucas County CHIP program. For homeowners in Lucas County outside Toledo city limits. It can cover a roof as a forgivable loan with no monthly payment, no interest and no credit check. Stay in your home five years and it’s forgiven. Income limits started at $53,100 for a one person household on the last flyer we saw, so double check the current numbers.
- Lucas County Land Bank Home Preservation Initiative. Connects homeowners with low interest repair loans through local banks, as long as you’re current on property taxes.
Financing through your roofer
For most people, this is the easiest way. You apply when you get your estimate. Approval is quick. The plan matches the real price of the job. At Roofing419 we offer two plans, subject to credit approval, because people are in different spots.
- No payment and no interest for 12 months. Built for people who have the money coming but not today. Maybe an insurance check is still being processed, or a tax refund or bonus is a few months out. You get the roof now and pay it off when the money lands.
- Payments as low as $99 a month with 0 down. For people who’d rather spread it out. Nothing out of pocket to get started, and a monthly number that fits a normal budget.
We’ll go over both, the full cost and your financing options during the free inspection, before you agree to anything. And look, ask every roofer these questions, us included. Get the answers in writing. If a roofer gets weird about that, it tells you something.
- What happens if I don’t pay it off in 12 months?
- What’s the rate on the monthly plan?
- Can I pay early without a penalty?
Personal loans
A personal loan doesn’t use your house as collateral. That’s the big plus. If life goes sideways, your home isn’t on the line. Money usually comes fast too. The downside is the rate can be all over the place depending on your credit. Strong credit might get single digits. Weaker credit can land in the 30s. Many lenders want a score around 620, and the best rates usually go to people over 700.
Here’s real math on a $15,000 roof. At 9% for 10 years you’d pay about $190 a month, roughly $22,800 total. At 18% for 5 years it’s about $381 a month, and the total ends up almost the same, around $22,850. Funny how that works. The lower payment isn’t automatically the better deal. Always look at the total. These numbers are just examples, your rate will depend on you and the lender.
Home equity loan, HELOC or cash out refi
Got equity in your house? Borrowing against it usually gets a lower rate than a personal loan. Most lenders want you to keep about 20% equity after. It takes longer though. Appraisal, paperwork, closing. Fine if the roof can wait a few weeks, not so fine if water’s coming in the kitchen. The interest might even be tax deductible if you itemize, but ask a tax pro before you count on that.
Just remember your house is the collateral. And be careful with a cash out refinance. If you locked in a low mortgage rate a few years back, refinancing the whole thing at today’s rates to cover a $15,000 roof could cost you way more than the roof. Do the math on the full mortgage. Not just the new money.
FHA Title I and USDA 504 loans
FHA Title I loans come through HUD approved lenders and can go up to $25,000 on a single family home. You don’t need equity. The tricky part is finding a lender that still offers them. We honestly don’t know how many Toledo area lenders do right now, so call around and ask for it by name.
USDA 504 loans have a 1% fixed rate for very low income homeowners. But only in eligible rural areas, and most Toledo addresses won’t qualify. If you’re out on the rural edge of the county, check the USDA map. It takes two minutes.
Credit cards and cash
A credit card is fine for a small repair or covering your insurance deductible. Maybe a true 0% intro card if you’re sure you can pay it off in time. Putting a whole roof on a regular card though? That’s about the most expensive way to do it. Try everything else first.
Cash is cheapest. No interest, no forms. But please don’t wipe out your emergency fund for a roof. Because the furnace will die in February. It always does. A lot of folks do a mix, some cash down and finance the rest. Smaller loan, smaller payment, less interest.
What if your credit isn’t great?
You can still get a roof financed. You’ll just have less options. There’s no one magic score, every lender sets their own. A co-signer with better credit helps alot. A secured loan can help too. And remember CHIP in Lucas County doesn’t check credit at all if you qualify on income and where you live.
If the roof can hold on for a season, even a small bump in your score could get you a better rate. But if it’s leaking right now, don’t wait. An emergency roof repair can stop the water and give you breathing room to figure out the money part.
So which one is right for you?
Find your situation below. Most homeowners fit one of these pretty clearly.
- Storm damage? Call your insurance first.
- Waiting on an insurance check or tax refund? A no payment, no interest for 12 months plan gets the roof done now so you can pay when the money comes in.
- Want a low monthly payment with nothing down? A $99 a month plan with 0 down is the easy route.
- Tight budget overall? Check Habitat, CHIP or the Land Bank before anything else.
- Plenty of equity and no rush? A home equity loan usually costs the least.
- Credit a little bruised? Roofer financing or a co-signer is probably your best bet.
Whatever way you go, it starts with knowing the real number. At Roofing419 we do a free 19 point inspection, show you photos of everything we find, and hand you a written quote. Our own crew does the work. No subcontractors. And it’s backed by a 25 year workmanship warranty. With no payment and no interest for 12 months, or 0 down and payments as low as $99 a month, you don’t need to have it all saved up. Call us at (419) 509-0456 or request your free estimate.
Questions people ask us all the time
Can I finance a new roof?
Yes. Most Toledo homeowners go with roofer financing, a personal loan or a home equity loan. Some qualify for local programs that cost little or nothing.
Does Roofing419 offer financing?
We do, with two plans. No payment and no interest for 12 months, or payments as low as $99 a month with 0 down. Both are subject to credit approval. We’ll go over them with you at your free inspection.
What credit score do I need to finance a roof?
There isn’t one magic number. Lots of lenders approve around 620, and the best rates usually go above 700. Lower scores can still get approved with a co-signer or a specialty lender.
How long can I finance a roof?
Depends on the loan. Promo plans can be 6 to 18 months. Personal loans often run 3 to 10 years. Home equity loans can go longer.
Should I pay cash or finance?
Cash is cheaper since there’s no interest. But a no interest plan paid off in time costs the same as cash and lets you keep your savings. Financing also makes sense when waiting would make the damage worse.
Can I get a new roof with no money down?
Yes. Some roofers offer 0 down financing. At Roofing419, payments start as low as $99 a month with nothing down, subject to credit approval.
Will my homeowners insurance pay for a new roof?
Usually for sudden damage like wind, hail or a falling tree. Not for age or wear. Older roofs on actual cash value policies may only get a depreciated payout.
Are there roof grants in Toledo?
The city’s Rooftops program is closed right now. If you’re in Lucas County outside the city, look at CHIP. Maumee Valley Habitat for Humanity also helps income eligible homeowners.
What’s the monthly payment on a $15,000 roof?
Depends on the rate and term. About $190 a month at 9% for 10 years. About $381 a month at 18% for 5 years.